

myFICO - Credit Score Tracking
by FICO
4.3
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.3
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
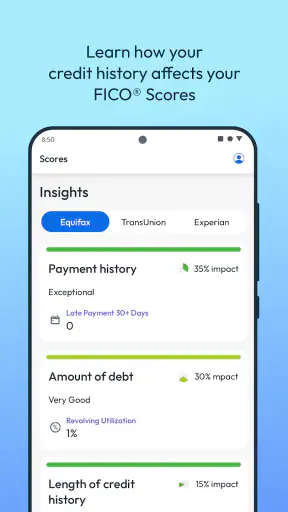
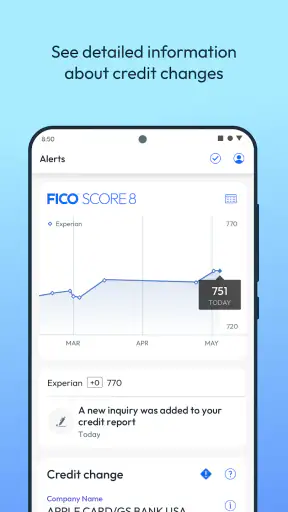
 Analysis by Getfullapps
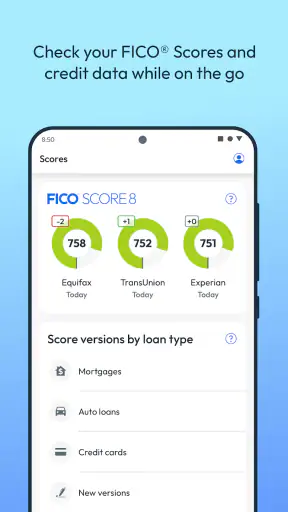
I came away from myFICO with the impression that it is best understood as a focused credit-monitoring companion rather than a complete personal-finance app. It is built for people who want to keep an eye on their FICO Score and Equifax credit report in one place, especially when preparing for a credit card application, a mortgage, or another major loan. I like that narrow purpose because it keeps the main task obvious: open the app, review your credit picture, and decide whether anything needs attention.
The app is free to install, developed by FICO, and listed for everyone. It has been available since August 18, 2015, and its current version is 4.0.23.4. Those details matter because this is not a brand-new experiment with an untested identity. It has had time to become familiar to a large audience, while the current version shows that the product is still being maintained rather than simply left untouched.
At the same time, I would not recommend treating any credit-score app as a magic answer to financial decisions. A score is a useful signal, but it is not the full story behind a lender's decision. The real value here comes from using the app consistently, understanding what you are looking at, and checking the underlying report instead of reacting to a single number.
How the current myFICO experience works in everyday use
The first thing I noticed is how naturally the app fits a specific routine. I can imagine opening it before applying for a new card, checking the report after moving, or reviewing my credit before speaking with a lender. Rather than searching through several financial services, I have a dedicated place for the score and Equifax report that matter to the app's purpose.
That makes it particularly useful for someone who is trying to replace guesswork with a regular review habit. A quick check can prompt a closer look at account information, balances, payment history, or unfamiliar activity. The important workflow is not merely viewing the score. It is noticing a change, opening the report, and deciding what action is appropriate.
A realistic example would be planning for a mortgage. I would not open the app once on the morning of an application and assume the result predicts approval. Instead, I would use it earlier to understand my starting point, inspect the Equifax report for errors, and avoid making rushed credit decisions based on anxiety. If something looked unfamiliar, the report would give me a more useful place to investigate than the score screen alone.
The same approach works for a credit-card application, though with a different level of urgency. Someone comparing cards may use the app to check whether their credit profile appears ready for another application. I find that helpful as a pause button: it encourages me to review the situation before adding a hard inquiry or taking on another account. It does not make the decision for me, but it can improve the timing of that decision.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
The app's narrow focus is also its first major trade-off. It is not designed to replace budgeting, bill payment, spending categorization, savings planning, or debt payoff software. If I wanted a complete view of monthly cash flow, I would choose a broader finance app and use this one only for credit monitoring. Trying to make it serve both roles would create unnecessary friction.
Why the report matters more than the headline score
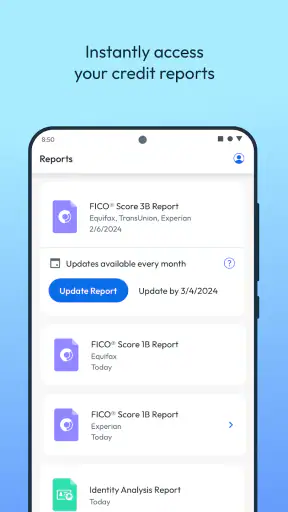
A score is easy to remember, which is precisely why it can be misleading when viewed alone. The report provides context. If the number changes, I want to know whether the cause is a newly reported balance, an account update, a missed payment, a new inquiry, or information that does not belong to me. The practical benefit of having the report close to the score is that it shortens the path from noticing a problem to investigating it.
My advice is to treat the score as a prompt, not a verdict. I would record the date of a check, note any meaningful change, and then read the report sections carefully. That simple habit is more valuable than repeatedly refreshing the score without understanding why it moved.
This is also where expectations need to stay realistic. A credit report can help me find information to question, but the app itself does not turn an observation into a correction. I still need to follow the appropriate process outside the app if an account or entry appears wrong. The application is most useful as an organized starting point for that work.
What the long-running product history tells me
Because the app dates back to 2015, I see it as a mature product in a category that has changed considerably over time. Its continued presence gives it a more established feel than a newly launched score tracker. The current version, 4.0.23.4, also suggests an ongoing product cycle rather than a frozen release.
Still, a version number by itself does not tell me that every part of the experience has changed dramatically. I would separate what is visible now from what I might hope to see later. The current evidence is straightforward: the app remains available, is maintained under the FICO name, and centers on FICO Score and Equifax report access. Expectations about future tools, broader bureau coverage, or deeper financial planning should remain expectations rather than assumptions.
For existing users, that distinction is reassuring. People who already use the app are not being asked to learn an entirely different kind of product simply because the version has advanced. The core reason to open it remains recognizable. A user returning after time away should still approach an update by checking the current display, reviewing account access, and confirming that the report information is what they expect before relying on it for an important decision.
New users benefit from the same continuity, but they should not confuse familiarity with completeness. A mature credit app can be dependable for its central task while still leaving other financial needs to separate tools. In my view, that is the right way to judge this product: ask whether you need credit visibility, not whether it can manage your entire financial life.
Useful routines for different kinds of borrowers
For someone rebuilding credit, I would use the app as a progress journal rather than a daily scoreboard. Checking too often can make normal movement feel like a crisis. A more sensible routine is to review the report at a consistent interval, look for changes, and connect those changes with actions already taken. The goal is to understand trends and accuracy, not chase every small fluctuation.
For someone with strong credit who is preparing for a major purchase, the report review becomes a form of preparation. I would look for outdated addresses, unfamiliar accounts, and reporting details that could complicate an application. This is a non-obvious strength of a combined score-and-report workflow: it helps shift attention from “What number do I have?” to “Is the information behind this number correct and understandable?”
For a parent helping a young adult learn about credit, the app can support a conversation about reports and responsible borrowing, but I would not hand over the score as if it were a grade. The useful lesson is how payment behavior, account management, and applications can affect a credit profile over time. The app can make that discussion concrete, while the parent still needs to explain the limits of any score.
For someone dealing with possible identity theft, I would use the report view as an inspection tool and act promptly if an account looks unfamiliar. The key trade-off is that visibility is not the same as resolution. Finding a suspicious entry is valuable, but the follow-up work may involve contacting the relevant company or using formal dispute and identity-protection channels. The app helps me notice; it does not remove the need to respond.
Where it compares well with ordinary alternatives
The usual alternative is a general banking or personal-finance app that shows a credit estimate alongside spending and account balances. Those services can be more convenient when I want everything in one dashboard. They may be the better choice for someone whose main goal is budgeting and who only occasionally glances at credit information.
myFICO makes more sense when the quality and context of the FICO-focused view matter more to me than having a broad financial dashboard. A person preparing for lending decisions may prefer a dedicated destination instead of treating credit as a small tile among transactions, subscriptions, and savings goals. The advantage is concentration; the disadvantage is that I need another tool for the rest of my finances.
It is also important not to assume that every score displayed by every service means exactly the same thing. Different financial products and lenders can use different scoring models or bureau information. I would therefore use this app to monitor the information it presents and to spot changes, not to promise myself that the displayed number will be identical to the number used in every future decision.
That nuance is one of the most important reasons I would recommend reading the report as well as the score. A general-purpose alternative may be perfectly adequate for casual awareness. A dedicated FICO experience is more compelling when I want a credit-specific habit and understand that monitoring is not a guarantee of a particular lending outcome.
Points that may frustrate careful users
The first limitation is scope. If I expect a budget planner, investment overview, debt calculator, or bill organizer, I will be disappointed because those are not the reason to choose this app. Its focused design is helpful only when my question is specifically about credit standing and the Equifax report.
The second limitation is psychological. Credit tracking can encourage compulsive checking, especially before a major application. I would resist opening the app repeatedly throughout the day. A planned review is more useful than constant monitoring, and a score change should lead to investigation rather than panic.
The third is interpretive. Even with a report available, I still need to understand which details matter and which changes are routine. A person new to credit may need outside education to make sense of the information. The app can put the material in front of me, but it cannot replace careful reading or professional advice for a complicated borrowing situation.
I would also be cautious about using the app as the only source for a high-stakes decision. Before applying for a mortgage or substantial loan, I would compare the app's information with the lender's requirements and ask which scoring approach is relevant. That extra step prevents a common mistake: assuming that one monitored score completely represents every underwriting process.
Access, cost, and practical expectations
The app is free, which lowers the barrier to trying it for people who want a dedicated credit-monitoring starting point. I still recommend reading the current in-app terms and screens carefully before relying on any particular service behavior. “Free” makes installation easier, but it does not remove the need to understand what information is being shown or how often it is updated.
It requires a minimum operating system of iOS or Android version 12, so compatibility is an important first check on an older phone. On a supported device, I would keep the app updated and protect access with the phone's normal security features. Credit information deserves the same care as banking information, even when I am only checking a report.
The app is rated for everyone, but that does not mean every user will find the subject matter equally simple. A teenager may be able to open it, yet the meaning of credit reports and lending decisions still requires context. For adults managing applications, rebuilding credit, or checking for inaccuracies, the purpose is much clearer.
Its audience size also indicates that it is not an obscure utility: it has more than a million installs, around twelve thousand ratings, and an average rating of 4.3. I mention that only as a sign of broad adoption, not as proof that it will suit every person. A popular app can still be the wrong fit for someone who needs budgeting or a different kind of credit view.
What I would watch as the product continues
With the current release at 4.0.23.4, I would watch how future updates affect the balance between a simple credit check and a more informative report-reading experience. The best evolution would preserve the quick overview while making it easier to understand meaningful changes without burying the user in financial jargon.
I would also pay attention to whether the app remains clear about the difference between monitoring and prediction. The most responsible experience is one that helps me inspect my information without implying that a score guarantees approval, a rate, or a particular lender response. That clarity matters more to me than adding decorative features.
Existing users should watch for changes in navigation and report presentation after updates, especially if they have built a regular review routine. New users should first establish what they want from the app: a credit check before applying, ongoing report awareness, or help investigating a possible error. Defining that purpose makes it easier to judge whether the app is delivering value.
I would not wait for a future update to develop good habits. The most useful workflow is already available in principle: check the score, open the report, identify anything unfamiliar, record meaningful changes, and take appropriate action outside the app when necessary. That sequence turns a passive glance into a practical credit-management routine.
My recommendation after using it
I recommend myFICO to people who want a dedicated place to monitor their FICO Score and review an Equifax credit report, particularly before a credit-card, mortgage, or loan decision. I appreciate its focused purpose, its established history under FICO, and the way a report can add context to a number that would otherwise be easy to misunderstand.
I would skip it as a primary finance app if my main need is budgeting, spending analysis, savings goals, or debt planning. I would also avoid relying on it as a guaranteed preview of every lender's decision. In those situations, a broader financial tool or direct guidance from the relevant lender may be more appropriate.
For the right user, the strongest benefit is not simply seeing a score on a screen. It is building a calmer, more informed process around credit: review the information, question what looks wrong, and make borrowing decisions with more preparation. That makes this free finance app worth considering, provided I use it as a monitoring and report-review tool rather than as the complete answer to my financial life.
Pros
- Shows FICO Scores used by many lenders.
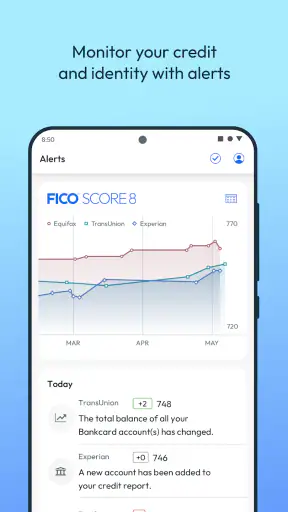
- Tracks score changes and provides historical trends.
- Offers identity theft monitoring on eligible plans.
- Includes personalized explanations for score factors.
- Provides access to credit reports with some memberships.
Cons
- Most useful features require a paid subscription.
- Score updates may not be available daily on every plan.
- Pricing can be high for users needing basic score checks.
- Credit scores may differ from those used by some lenders.
- Some alerts and monitoring tools depend on plan level.
FAQs for myFICO - Credit Score Tracking
What is myFICO – Credit Score Tracking used for?
myFICO – Credit Score Tracking is designed to help users monitor their FICO credit scores, review credit-report information, and understand the factors affecting their credit profile. It can be useful when preparing to apply for a loan, credit card, mortgage, or other financing. The app presents score information and related insights in a more convenient format than checking through a web browser, although the exact features depend on the plan you choose.
Does myFICO provide the same credit score that lenders use?
myFICO focuses on FICO Scores, which are widely used by lenders, but there is not just one universal FICO Score. Different lenders may use different versions and scoring models depending on the type of credit being requested and the credit bureau involved. Therefore, the score shown in the app can be valuable for tracking your credit health, but it may not exactly match the score a particular lender checks at a specific time.
Is myFICO free to download and use?
The app may be available to download without an upfront charge, but access to complete score monitoring, reports, alerts, and additional credit features generally depends on a paid myFICO membership or subscription. Before signing up, review the current pricing, billing frequency, trial conditions, and cancellation rules shown in the app store or on the official service. Availability and included features can vary by plan and location.
How often are credit scores and reports updated in myFICO?
Update frequency depends on the myFICO plan and the specific monitoring service included with your account. Credit bureaus receive information from lenders on different schedules, so changes to balances, payments, or accounts may not appear immediately. Even when the app refreshes successfully, there can be a delay before a lender reports new information. Users should treat the app as a monitoring tool rather than a real-time credit display.
Is my personal and financial information safe in myFICO?
Because myFICO handles sensitive identity and credit information, users should review its privacy policy, security details, and requested permissions before creating an account. Use a strong, unique password and enable any available account-protection options. Avoid accessing the service on unsecured public networks, and download only the official app from a trusted store. No service can guarantee zero risk, so regularly checking account activity is still important.

myFICO - Credit Score Tracking
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via myfico_android@fico.com, visit http://www.myfico.com, or review their https://www.myfico.com/policy/privacy-policy/.










